Tax authority bars unsupported demands when businesses close tax codes
Vietnam's tax authority told local offices not to demand unsupported documents or procedures when businesses close tax codes, VnExpress reported.
KBVN+ desk·15 September 2026·1 min readOriginal reporting published:
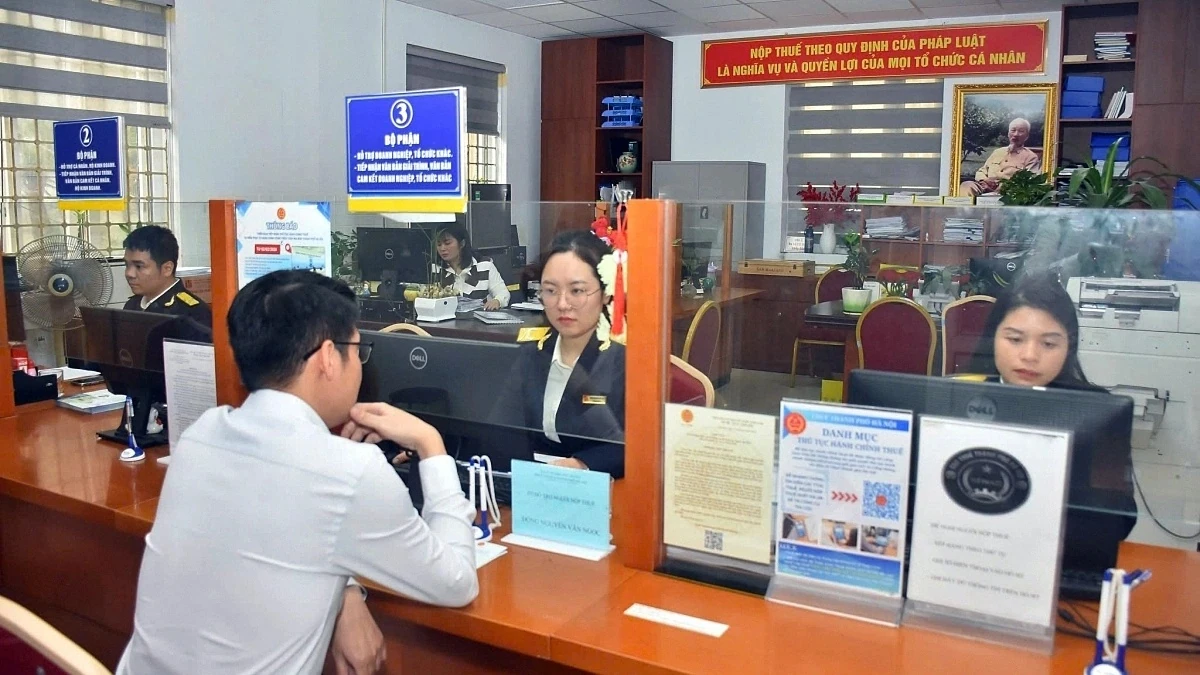
Photo: VnExpress Kinh doanh
Offices must clearly publish requirements and obligations. Where the evidence is sufficient, outstanding amounts and required actions should be communicated together in a single complete notice.
Confirmation must be issued within three working days once tax obligations are fulfilled. The instructions aim to reduce backlogs and inconsistent handling.
Sources & further reading
Open the original reporting and reference material.