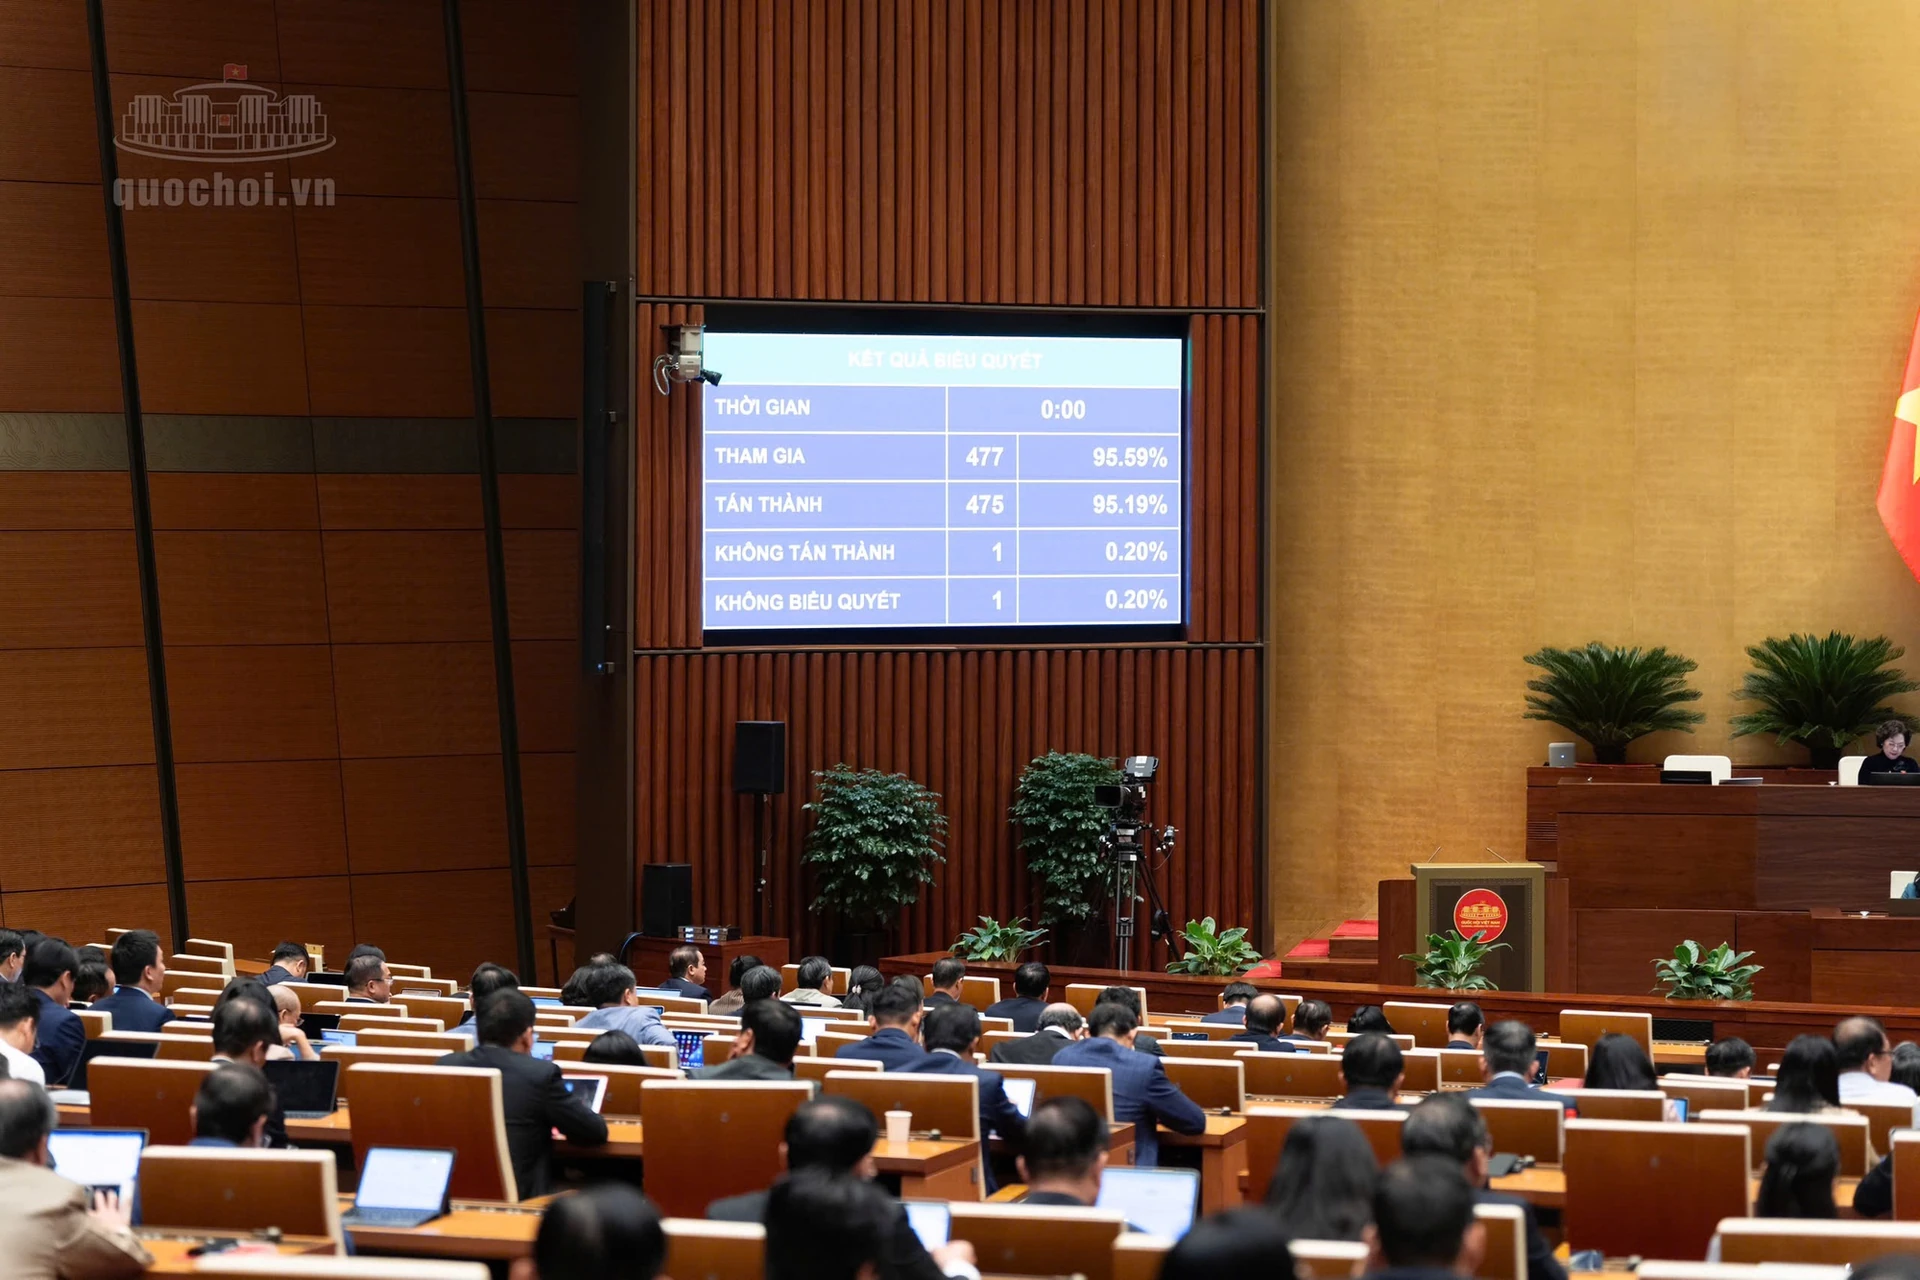
Vietnam’s National Assembly passed a law amending provisions in three tax laws on the afternoon of 20 November. Government News reported that 475 of the 477 delegates taking part in the vote supported the measure, which covers corporate income tax, non-agricultural land-use tax and personal income tax.
The law generally takes effect on 1 January 2027, according to the government’s policy portal. Some provisions have separate dates. The VND 10 billion revenue threshold for businesses and individuals earning business income to choose a calculation method applies from the 2027 tax year. A 0.2% rate for abandoned land takes effect on 1 July 2027, while the provision on land prices used to calculate non-agricultural land-use tax takes effect on 1 January 2028.
Income tax and smaller firms
Government News reported that small and medium enterprises are exempt from corporate income tax for three years from the date of their first enterprise registration certificate. The rule concerns a specified class of firms and registration date. It is not a three-year exemption for every company.
The government’s explanatory report says a future decree will exclude certain businesses formed through mergers, consolidation, division or conversion, and certain new firms established after another firm with the same owner or controlling members or shareholders is dissolved. That exclusion is described as forthcoming implementing guidance, not a determination of any individual firm’s eligibility.
The amended provisions also add certain expenses incurred by large or lead firms for training, technical advice, product improvement and technology-transfer support for SMEs in their value chains to deductible costs. The law and relevant guidance determine the detailed scope and conditions.
Land and personal income
The amendments address taxable non-agricultural land area and add an exemption for land used for education and training within the scope stated in the law. The explanatory report says the planned implementing rules exclude areas used for business, commercial or service purposes.
Another provision exempts resident individuals’ income from supplying meals to education and medical establishments under the relevant legislation. Its scope is specific and does not extend automatically to every food service.
KBVN+ previously covered plans to simplify tax calculations and income tax relief under Decree 398. Those earlier measures have their own scope. The afternoon tax law is also separate from the SME development law passed that morning.