Further tightening is not a fixed timetable
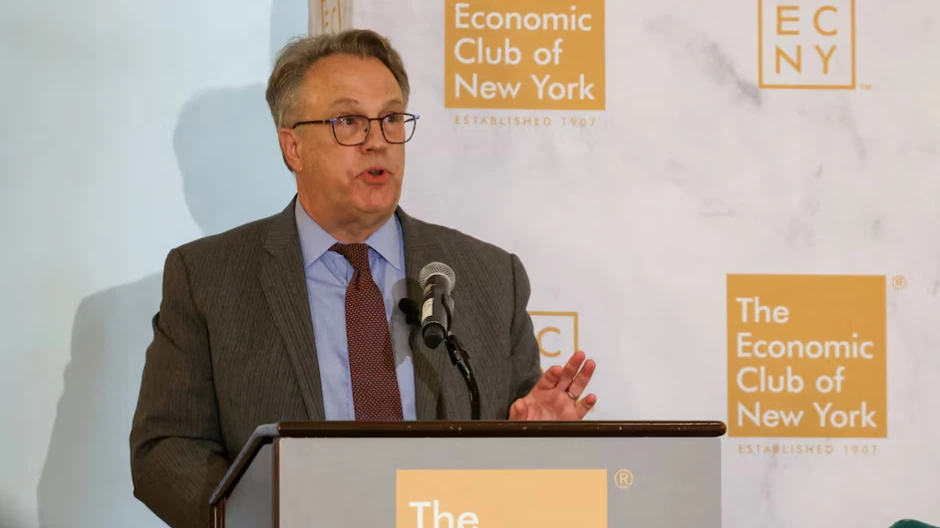
Williams maintained his view that another increase this year could be suitable. However, he emphasised that it was only mid-October and that numerous forces were affecting the economy, making continued monitoring necessary.
The article recalled the Fed's 25-basis-point increase in the previous month, its first in more than three years. Williams subsequently said there was no need to hurry. Those comments help explain market expectations ahead of the late-October meeting; they do not determine its outcome.
Inflation and energy remain central
Williams identified high energy prices linked to Middle East conflict as a near-term pressure and also discussed technology-related investment. He nevertheless expected inflation to move closer to the Fed's 2% target in 2027 as tariff effects recede.
He said the economy was not currently overheating. Together, these observations describe the scenario behind his assessment rather than a guaranteed rate path. His position as FOMC vice-chair makes the remarks significant, but policy requires a collective decision. Fresh economic releases and the next formal meeting announcement will establish what the Fed actually does.